

Affirm: Buy now, pay over time
4.8

In a shared household, a purchase can affect more than the person at checkout. I’d treat Affirm as a personal payment tool rather than a family wallet: one person can consider a purchase, but the repayment commitment belongs in that person’s budget. That distinction matters when a partner, roommate, or relative shares the device or helps manage household spending.
Keep the account and the decision personal
On a shared phone or tablet, I would avoid leaving a financial app open where someone else could browse account details or make a decision in my name. The practical boundary is simple: the person applying should enter their own information, review the terms themselves, and keep track of the resulting payments. I would not use another household member’s account or assume that sharing a device means sharing responsibility.
Before starting an application, it helps to pause and ask whether the purchase is genuinely needed now, whether the expected payment fits after ordinary bills, and who will be responsible if plans change. That short check is especially useful for shared purchases such as a household appliance: agree on the item and who is paying before checkout, rather than sorting out ownership and installments afterward.
Coordinate around the calendar, not just checkout
Installments can make a large purchase feel smaller in the moment, but they still occupy room in a future budget. I’d note the payment dates alongside rent, utilities, subscriptions, and other regular expenses instead of relying only on a reminder from an app. A reminder is helpful; it is not a substitute for knowing what is due and making sure the payment account is ready.
For couples or roommates, a quick conversation before using a pay-over-time option can prevent an awkward mismatch. Decide whether one person is buying the item and the other is contributing, or whether the purchase should wait until the household has saved for it. If the plan depends on someone else sending money later, I’d be cautious: the account holder still needs a workable plan if that contribution arrives late.
Who benefits—and who may be better off waiting
Affirm: Buy now, pay over time is most useful for adults who already have a clear budget, understand the payment schedule shown for a specific purchase, and want another way to spread a cost. It can be convenient when a necessary replacement cannot reasonably wait, or when a planned purchase has a repayment amount that fits comfortably without displacing essentials or savings.
I would skip it for impulse buys, uncertain income, or purchases that only seem affordable when viewed as a small installment. If paying in full is realistic and does not strain the household, that is usually the simpler route: there is no future payment to remember. A standard credit card may also suit someone who pays its balance reliably and prefers to keep spending and repayment in one familiar place. Neither alternative is automatically cheaper; compare the actual terms and total cost before choosing.
If an unexpected expense is the reason for considering installments, I’d first compare the available plan with waiting, using savings, or asking the retailer about its ordinary payment options. The right choice depends on the terms at checkout and the rest of the budget, not on a general promise that splitting payments is always easier.
Getting Started with Affirm
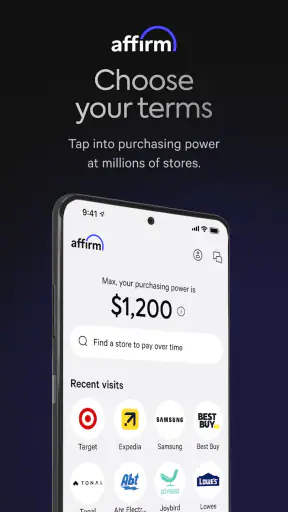
So, first things first, downloading the app is a breeze. Available on both Android and iOS, it’s just a couple of taps away in the app store. Once installed, you’re welcomed with a clean and intuitive interface. Creating an account is straightforward, requiring just basic info like your name, email, and phone number. It’s worth noting that Affirm does a soft credit check, which won’t affect your credit score, just to ensure everything’s legit on their end.
How Affirm Works
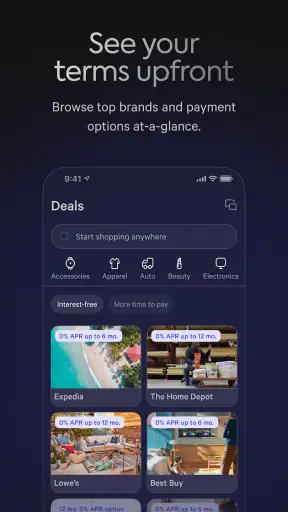
Now, here’s where Affirm gets interesting. The app partners with a plethora of retailers, from electronics to travel, allowing you to split purchases into manageable payments. When you’re ready to checkout, you’ll see the option to pay with Affirm alongside the usual credit card options. Click on it, and you’re presented with different payment plans. You can choose to stretch your payments over 3, 6, or even 12 months.
The beauty of Affirm is its transparency. No hidden fees, no surprises. What you see is what you get. They show you the interest upfront (if there is any), so you know exactly what you’re signing up for. Sometimes, you might even score a zero-interest plan, making that splurge a little less guilt-inducing!
Features That Stand Out
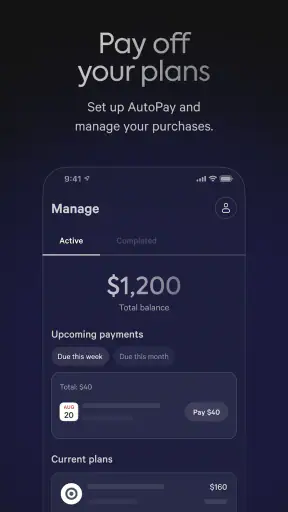
One feature I particularly like is the ability to track your spending and payments right within the app. It gives you a snapshot of your financial commitments, helping you stay on top of things. Plus, the notifications remind you of upcoming payments, so you’re never caught off guard.
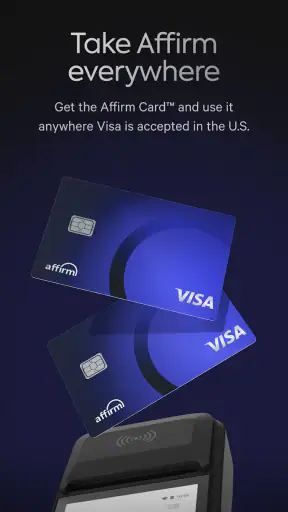
Another nifty feature is the virtual card, which you can use at any online retailer. This means you’re not limited to Affirm’s partnered stores. Just set your spending limit, generate a virtual card, and shop away. It’s like having a credit card without the physical plastic.
Use the plan details as a budgeting tool
A useful habit is to check the complete repayment picture before deciding: the amount due, the schedule, and any interest shown for that offer. I would compare the total against the cost of paying now, rather than judging a plan by its first installment. If I’m shopping for a household item, I’d also make sure the agreed budget reflects the full cost, not just the portion one person expects to cover.
The in-app payment overview can help when several commitments overlap, but I wouldn’t treat it as a full household budget. It is a view of Affirm-related payments, not a reason to stop checking bank balances or other bills. For a shared-device household, each person should keep their own payment information private and make sure reminders reach the account holder who is responsible.
Why Consider Using Affirm?
So, why should you consider using Affirm? For one, it’s about flexibility and control. It allows you to make those big-ticket purchases without the immediate financial strain. It’s also a great tool for budgeting. Instead of blowing a hole in your bank account, you can plan your finances better.
Moreover, Affirm is a godsend for those who want to avoid high-interest credit card fees. The app’s transparent approach means you’ll never pay more than you expected. It’s all about giving consumers the power to decide how they want to pay.
Read the offer before committing
Plans can differ from one purchase to another, so I would not assume that an offer seen once will apply to a different item or retailer. At checkout, take a moment to review the terms attached to that particular purchase and consider whether the schedule still works if another bill lands in the same period. A plan that looks manageable in isolation can feel less comfortable when several obligations come due together.
For travel or other purchases where dates may shift, I’d be particularly careful about coordinating the payment commitment with the household’s plans. Make sure the person accepting the plan understands what they are agreeing to and can manage it even if another person’s contribution changes. This is a practical safeguard, not a special household feature: the app does not replace an explicit conversation about who is responsible.
Age, trust, and a sensible boundary
The app is rated Everyone, but that content label is not a recommendation for children to take on payment commitments. I would keep account access and purchase decisions with the adult who is financially responsible. If a younger family member shares a device, explain that the app is for managing an individual’s payment choices, not a household allowance or permission to buy something.
Affirm is developed by Affirm, Inc. It is a shopping app rather than a general-purpose budgeting service, so I’d use it for evaluating and tracking its own payment arrangements while keeping broader household planning elsewhere. That separation makes it easier to see what the app can help with—and what still requires a conversation, a calendar, or a budget.
Where it fits among shopping payment options
Compared with paying by debit, Affirm can spread a purchase over time, but debit avoids adding future installments to the calendar. Compared with a credit card, the appeal is seeing a specific plan for a purchase rather than relying on a revolving balance; the trade-off is that the offer and repayment structure need to be judged individually. For a buyer who wants one simple transaction and has the money available, paying in full is less to manage.
The virtual card can be useful when a retailer does not present Affirm among its checkout choices, but it still calls for the same careful review of the terms before proceeding. I’d use it as a way to access a plan for a considered purchase, not as a workaround for a budget that cannot support the item. Convenience expands where you can shop; it does not make the purchase more affordable by itself.
Affirm is free to download, has an average rating of 4.8 from around 561,000 ratings, and has over 10 million installs. It is rated for Everyone, was released on June 20, 2016, and version 3.402.1 requires Android 7.0 or later. Those figures give a sense of its reach, but they do not tell me whether a particular payment offer is right for a particular household; the checkout terms and personal budget matter more.
Wrapping It Up
Overall, Affirm: Buy now, pay over time is a solid option for anyone looking to shop smartly and manage their money more effectively. It’s like having a financial buddy who’s got your back, making sure you enjoy the things you love without the stress. Whether you’re an avid online shopper or someone who just occasionally makes big purchases, this app is definitely worth considering.
So, next time you’re eyeing that new tech gadget or planning your dream vacation, remember that Affirm might just be the key to making it happen—without breaking the bank! Happy shopping!
My household verdict
I’d recommend Affirm to an adult who values a clear purchase-specific payment plan, checks the full cost, and can keep the responsibility firmly in their own budget. It may be a poor fit for anyone who is already juggling bills, buying on impulse, or counting on a partner or roommate to cover installments without a firm agreement. For shared purchases, decide together first and let the account holder make the final choice only when the plan works on their own numbers.
My most practical advice is to compare the offer with paying now, then write down the payment dates before leaving checkout. If the installments still feel comfortable after accounting for ordinary household expenses, the app can be a useful option. If they only work when everything goes perfectly, I’d wait or choose a simpler way to pay.
4.8
220.61K Reviews
Pros
- Simple user interface for easy navigation.
- Quick approval process for new users.
- Flexible payment plans to suit budgets.
- No hidden fees or surprise charges.
- Accepted at a wide range of retailers.
Cons
- Requires a credit check for approval.
- Interest rates can be high for some users.
- Limited to participating merchants only.
- No option for joint accounts or profiles.
- App lacks in-depth financial tracking tools.


